

Your monthly budget in Madison.
Madison pays well in health IT, biotech and the university, and living costs keep pace. Monthly shows what is left after bills, typed in by hand.
$0
Cost to use Monthly
At your pace
Start with your first entries
0
Bank accounts connected
100%
Your data stays yours
Sound familiar?
Bring your expenses in Madison together and get a clearer view of the month.
Without Monthly
- You don't know your real free money until you've already spent it
- Fixed expenses catch you off guard every month even though they're always the same
- You reach the weekend without knowing if you can go out without overspending
- Your savings and investments are scattered across different places with no unified view
- Spreadsheets are a pain and banking apps mix everything together with no structure
With Monthly
- You see your real free money from day one of the month, before you spend a dollar
- You enter all your fixed expenses once and Monthly carries them into every new month
- The weekend reserve is already set aside before the week even starts
- All your investments logged in one place, no APIs or complications
- Your monthly budget in one app you can use from your phone
Everything you need to plan your month in Madison
Monthly covers every part of your monthly finances, without the complications.
Paycheck and real free money
Enter your paycheck in Madison and Monthly instantly calculates how much free money is left after every commitment for the month.
Fixed expenses under control
Rent, utilities, card payments and subscriptions in Madison organized in one place. No surprises at the end of the month.
Weekend reserve
Set aside money for going out before you spend it. Four weekends, four reserves. Never reach Sunday wondering where it all went.
Investments and savings
Log your savings, retirement account, brokerage holdings or anything else. No APIs or live prices. Just your own numbers, always at hand.
Money owed to you
Lent money to someone? Log it in Monthly. Nothing forgotten, nobody made to feel awkward about asking for it back.
Optional AI assistant
Ask about your records and review your budget with the assistant. You choose whether to enable it and which decisions to make.
How to organize your month in Madison with Monthly
Start with your income and fill in your plan at your own pace.
Enter your paycheck
The starting point. Your take-home pay for the month, entered in seconds at the start of each period.
Add fixed expenses
Rent, utilities and card payments in Madison. Everything you already know is coming, in one place.
Set the weekend reserve
Decide how much you want available each weekend and Monthly sets it aside automatically from the plan.
Log investments and debts
Savings, retirement accounts, brokerage holdings, whatever applies. All noted down without relying on live prices.
See your real free money
The number that matters: how much you can spend without touching the rest of the month. No surprises, no guilt.
How to organize your month in Madison without constantly putting out fires
A concrete guide to lowering financial anxiety and gaining clarity with your paycheck, fixed expenses, reserves and investments.
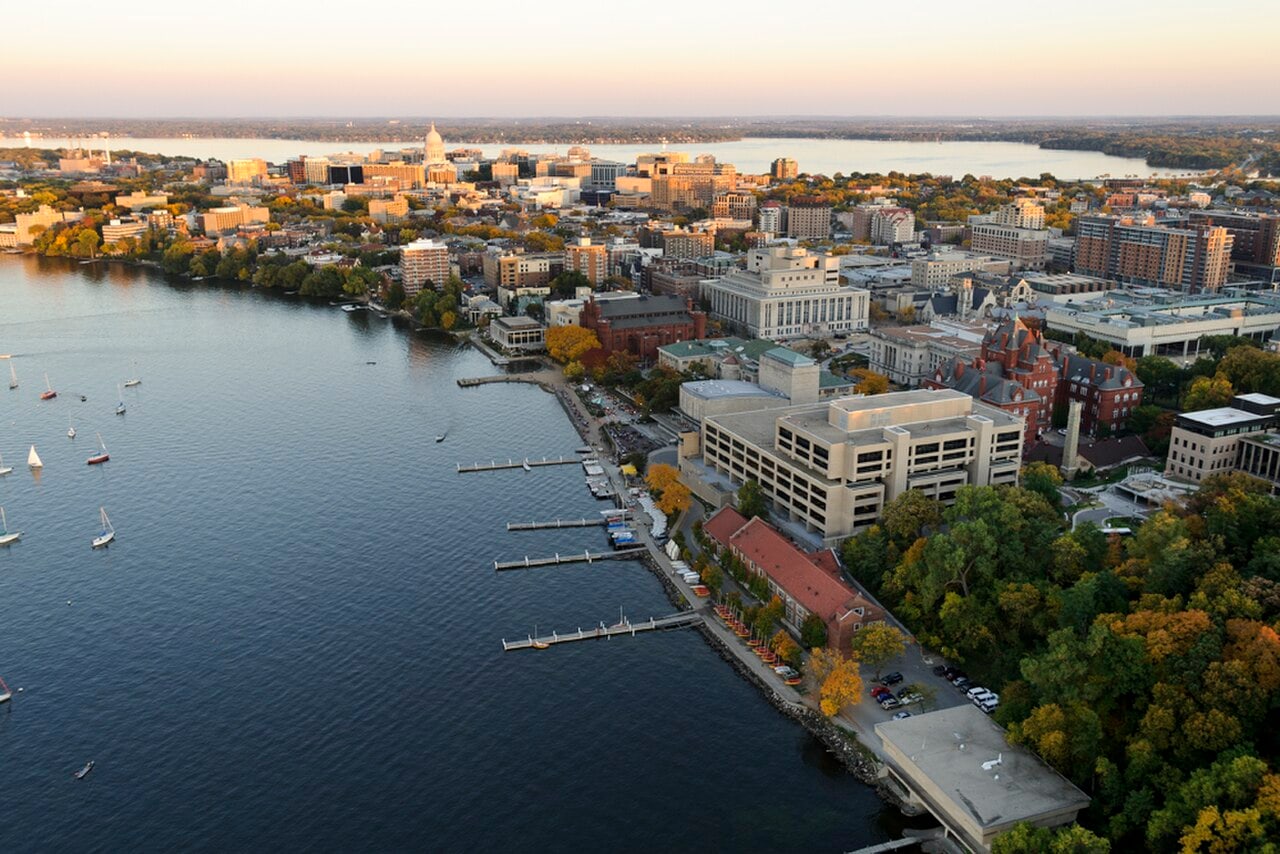
Madison combines a state capital, a flagship university and a health IT industry in a city of about 270,000 people. The 2020 census counted 269,840 residents, and Wikipedia says it was Wisconsin’s fastest-growing city as of 2024. Downtown sits on an isthmus between Lake Mendota and Lake Monona, and the city is the home of the Wisconsin State Capitol. The picture behind any budget app for managing money in Madison is a good paycheck in a city where housing and everyday costs have kept up with it.
The payroll behind the isthmus
UW-Madison, UW Health and state government are the largest employers, with the university alone employing more than 25,000 faculty and staff, according to Wikipedia. The largest private employer is Epic Systems, in the suburb of Verona. Biotech and health information technology companies such as Exact Sciences and Promega sit alongside information technology and financial services firms like American Family Insurance.
That is a mix of pay structures. A research scientist, a hospital IT analyst, a state agency worker, a graduate assistant and a software support engineer will each have a different payday and a different list of deductions. A single rule helps all of them: plan on the net deposit that arrives in your account, and enter anything extra, such as a bonus or a stipend, on the day it comes in.
When pay and prices both go up
A higher salary does not automatically create more free money. When pay grows in a place that draws tech and health workers, rent and housing tend to rise with it, and the household that raised its spending at the first raise finds the second raise already spoken for.
The remedy is to watch the difference between your income and your fixed bills, not just the income. Each time you accept a raise or renew a lease, enter the new numbers and compare the leftover. If rent went up by $150 and the raise brought home $120, you are behind, even though the paycheck looks bigger.
Where you live changes the math
Where you live in the area changes the budget. Downtown and the isthmus put you near work and the lakes, and often at a higher rent. Middleton and Fitchburg border the city, and Sun Prairie is its largest suburb, each with different rents and different drives. Verona is where Epic is based, so for many workers the question is rent in the city plus a commute against rent nearer work.
Do the comparison with real figures: rent, parking or a bus pass, gas and a monthly slice for car upkeep. Whichever place leaves more at the end of the month is the cheaper one, regardless of the sticker price on the lease.
Winter is a line in the plan
Madison winters are not mild. The city averages about 17 mornings a year at 0 degrees Fahrenheit or colder and around 52 inches of snow, according to Wikipedia. That shows up in heating bills, in a car that works harder, in boots and a coat and in the days you do not feel like walking anywhere.
List a winter version of your fixed expenses: heating, extra fuel, a snow service if your lease does not include one. Update them in November, not in January. A winter that was planned feels like routine. A winter that was not feels like a series of small emergencies.
Capitol Square on a Saturday
The Dane County Farmers’ Market, Concerts on the Square and the Art Fair on the Square all happen around the Capitol, according to Wikipedia. These are the events that make weekends in Madison feel full, and they are also the ones where a morning stroll can cost $50 without any single purchase feeling large.
The weekend reserve works best here as a weekly number. Pick an amount for Saturday and Sunday together, enter it before you go, and check how much is left on Sunday evening. The point is to find out whether the habit is a $40 habit or a $90 one, while it is still easy to adjust.
A health IT salary and a ten-month appointment
First, an invented health IT employee renting in the city. Net pay is $5,250 a month. Rent is $1,850, utilities $170, internet and phone $140, student loan $380, car payment and insurance $460, groceries as a fixed $520 and a gym and subscriptions line of $90. Fixed expenses total $3,610. With a $300 weekend reserve, the month leaves $5,250 minus $3,610 minus $300, or $1,340.
Second, an invented university employee on a ten-month appointment. Net pay is $3,300 for each of ten months. Rent is $1,150, utilities $150, phone and internet $120, transit and car $220, groceries $380 and student loan $210, so fixed expenses total $2,230. With a $140 weekend reserve, a monthly cost of $2,370, each school-year check leaves $3,300 minus $2,370, or $930. In the two months without a check, the household needs $4,740 in total. Setting aside $474 from each of the ten checks covers it and leaves $456 free per check.
First move: enter your net pay and your rent, then add the winter version of your utilities. Enter your net deposit and your rent, and see what a raise really left you →
Retirement plans, savings and roommates
A university or state retirement plan, a high-yield savings account and a brokerage balance can sit in the investments list, each with a typed balance and the date you checked. They stay notes; no account is connected and no investment is suggested. If a roommate still owes you for a security deposit or a utility bill, record it under money owed. The feature list shows every section.
Why typing it in beats a feed
For someone paid by a large institution, the deposit is predictable, and the work is in the bills. A budget built by hand shows each bill as you entered it, with no pending items or categories you did not choose. It takes minutes and it gets updated when something changes.
When the next paycheck arrives, start with the rent. Put in your rent and this month’s pay, then see how much of your raise is still yours →
Frequently asked questions about Monthly in Madison
Everything you need to know before you start.
I just started at a health IT company in Verona. What is the first mistake to avoid?
Do I live in Madison, Middleton, Fitchburg or Sun Prairie, and does it matter for the budget?
How do I plan a winter when Madison gets about 52 inches of snow?
I teach at the university. Is a ten-month contract hard to budget?
The Saturday farmers' market is a habit. Where does that money go in the plan?
YOUR NEXT MONTH STARTS HERE
Start organizing your month in Madison today
Free. No bank connection. Start with your first entries.
Create my free budget- Free to use
- No credit card
- No bank connection